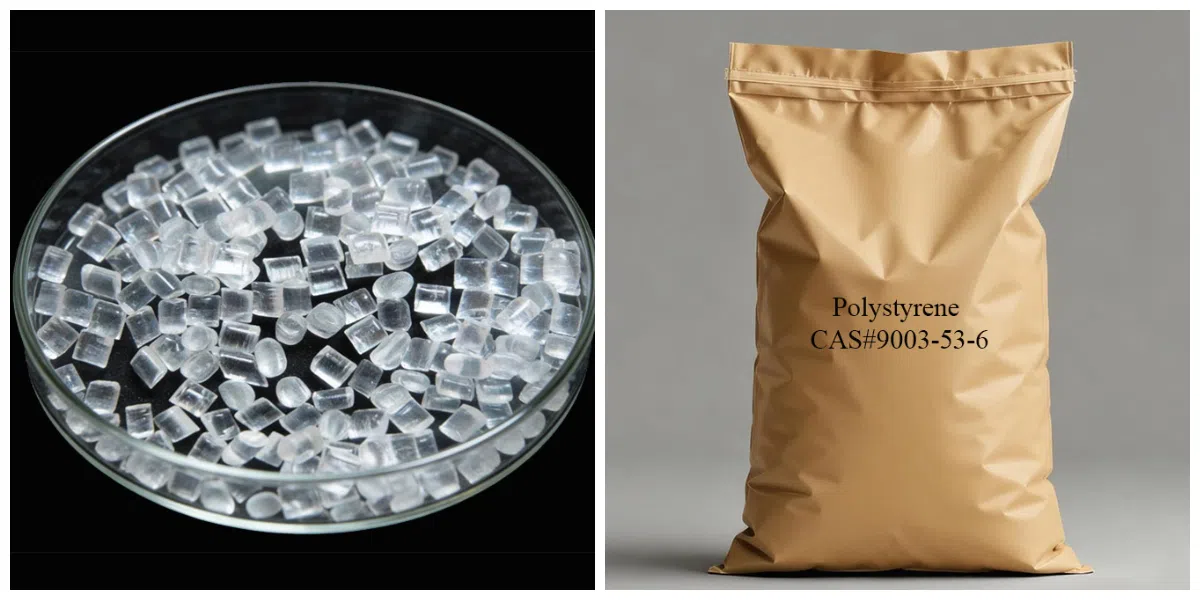
The global polystyrene (PS) industry is undergoing significant changes in 2026, driven by shifting trade flows, production capacity adjustments, and growing interest in plastic recycling.
According to ChemOrbis, China's polystyrene imports fell to record lows in the first half of 2026, while exports reached new highs. Expanding domestic production capacity has strengthened China's supply position and increased its importance in the international PS market.
Meanwhile, changes in overseas production capacity and new recycling initiatives are reshaping the industry's supply landscape. In the United States, transport-grade expanded polystyrene (EPS) packaging has gained renewed recognition within a major plastics circularity initiative, while South Korea is expanding efforts to recover waste polystyrene through pyrolysis.
For buyers and distributors, key factors to monitor include styrene feedstock costs, regional supply availability, freight rates, product specifications, and evolving environmental regulations.
As the market continues to adjust, reliable supply, consistent product quality, and competitive pricing remain important considerations for polystyrene procurement.